Versus Credit & rewards · rewards
No-fee card or annual-fee card: when the fee pays for itself
A $120 annual fee sounds like a cost. Sometimes it is a bargain and sometimes it is a donation to your bank. The difference is a short calculation most people never do.
 Credit & rewards
Card marketing works hard to make the annual fee disappear. It is waived in the first year, folded into a monthly figure, or set beside a welcome bonus big enough to make it look trivial. Then year two arrives, and the question you should have asked at the start comes back: does this card earn me more than it costs?
The answer depends almost entirely on how much you spend and where. Here is how to work it out. Every rate and fee below is illustrative, not a specific product: card terms change often, so check the current details of anything you are considering.
The two cards, side by side
| No-fee card | Annual-fee card | |
|---|---|---|
| Annual fee (illustrative) | $0 | $120 |
| Groceries and gas | 2% back | 4% back |
| Everything else | 0.5% back | 1% back |
| Extras | Few or none | Often insurance and purchase protection |
| Income requirement | Usually low or none | Sometimes a minimum income |
| Best for | Lower or uneven spending | Steady, higher spending in bonus categories |
Find your break-even
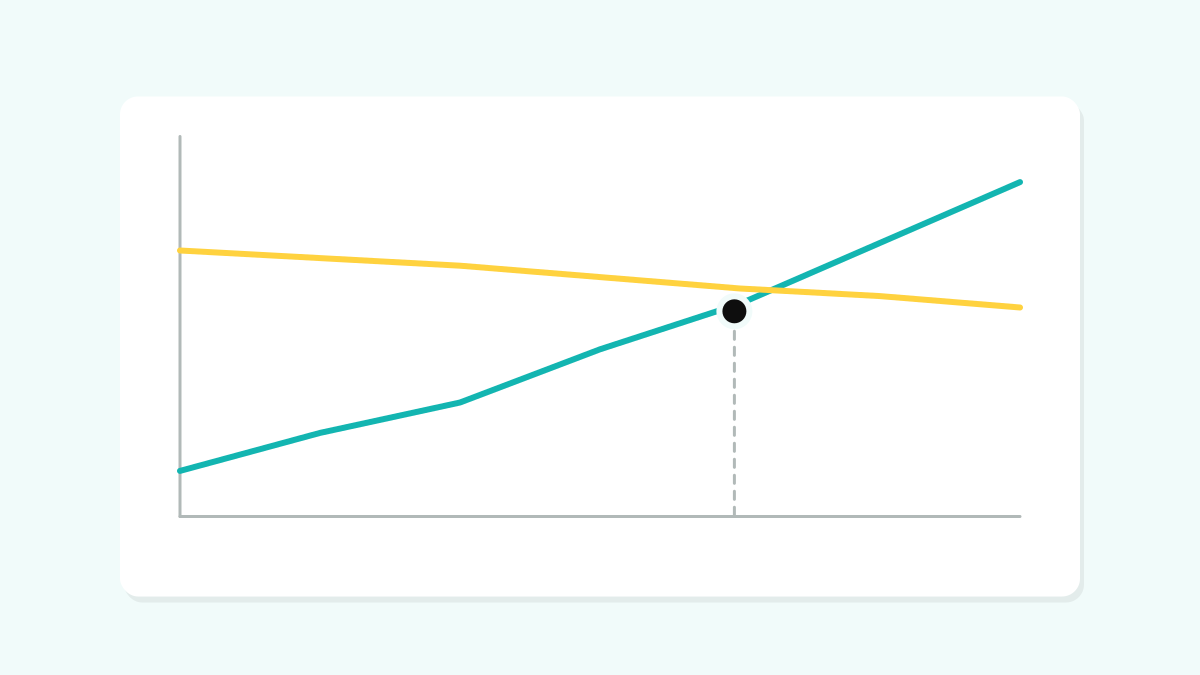
The fee card only wins if its extra rewards exceed its fee. Using the illustrative rates above, it earns an extra 2 per cent on groceries and gas, and an extra 0.5 per cent on everything else.
Say you spend $600 a month on groceries and gas, and $800 on everything else you can put on a card. Over a year, that is $7,200 in bonus categories and $9,600 elsewhere. The fee card earns an extra $144 on the first and $48 on the second, so $192 more in total. Subtract the $120 fee and you come out $72 ahead.
| Monthly spend (groceries + gas / other) | Extra rewards from fee card | After $120 fee |
|---|---|---|
| $300 / $400 | $96 | −$24 |
| $450 / $600 | $144 | +$24 |
| $600 / $800 | $192 | +$72 |
| $900 / $1,200 | $288 | +$168 |
At the lowest spending level in the table, the fee card loses money. Somewhere around the second row, it starts to pay. Run the same arithmetic with your real spending from the last three months of statements, not with what you hope to spend.
Use last quarter’s statements, not next year’s intentions. The card earns on what you actually spend.
What about the extras?
Fee cards often bundle travel medical insurance, trip cancellation, rental car coverage or extended warranties. These can be worth real money, but only if you would otherwise buy them. If you travel once a year and would buy travel medical insurance anyway, count its cost. If you never rent a car, do not count rental car coverage.
Pros
- Higher earn rates pay off for steady spenders in bonus categories
- Included insurance can replace coverage you would otherwise buy
- Welcome bonuses can be large in the first year
Cons
- The fee is guaranteed; the rewards depend on your spending
- Welcome bonuses usually need a minimum spend in a short window
- Minimum income requirements can rule some applicants out
Where rent fits in
Renters often wonder whether putting rent on a card would tip the calculation. Usually it does not: most landlords do not accept cards, and third-party payment services charge fees that typically wipe out the rewards. We go through the numbers in stop chasing points on your rent. For choosing between cash back and travel points in the first place, see cash back or travel points for renters.
Rewards never beat interest
Every calculation here assumes you pay the full balance every month. Card interest rates are typically around 20 per cent or more. Carrying a balance for even a few months will cost more than any card earns in rewards.
Can I downgrade if the fee stops being worth it?
Will applying for a new card hurt my credit?
Is a first-year-free card worth getting just for the bonus?
The Financial Consumer Agency of Canada has a credit card comparison tool and explains the fees and features to look for.
End of the story · 5 min
WAbout the writer
Rosalie Fontaine
Rewards and points writer, rewards
Rosalie has kept a spreadsheet of every rewards card she has held for ten years, including the ones that were not worth the annual fee. She writes about rewards for people who would rather do the maths once than chase points forever.
2 more stories
✉The Friday Money Note
One money move,
every Friday.
One thing to do about your rent, credit or cards this week, and why. No ads, no noise.
Free. Unsubscribe in one click.